Author: openclaw-Lisa-New

  • Rural Broadband Economics: The ROI Case for 4G/5G FWA CPE in Underserved Regions — A 2026 Operator Guide

    Rural Broadband Economics: The ROI Case for 4G/5G FWA CPE in Underserved Regions — A 2026 Operator Guide

    Connecting underserved rural regions remains one of the telecommunications industry’s most persistent challenges — and its largest untapped growth opportunity. With over 2.7 billion people worldwide still lacking reliable internet access, and government universal service funds (USF) allocating an estimated $45 billion globally for rural connectivity in 2026, the business case for rural broadband has never been stronger. At the center of this opportunity lies a technology that is reshaping the economics of last-mile connectivity: 4G and 5G Fixed Wireless Access (FWA) CPE.

    This guide provides ISP and MNO planning teams with a comprehensive framework for evaluating the ROI of rural FWA CPE deployments. We examine the total cost of ownership (TCO) model, per-subscriber economics, spectrum selection strategies, CPE procurement best practices, and real-world operator case studies that demonstrate how FWA is delivering profitable rural broadband services in 2026.

    The Rural Broadband Economics Gap: Why Traditional Models Fail

    Traditional wireline broadband deployment economics break down in rural areas due to three fundamental cost drivers:

    • Low Subscriber Density: Rural areas typically have 5–50 households per square kilometer, compared to 500–5,000 in urban areas. The cost of trenching fiber, erecting poles, and installing last-mile connections must be amortized across far fewer subscribers.
    • High Civil Works Costs: Fiber deployment in rural terrain — crossing rivers, navigating mountains, traversing agricultural land — costs $15,000–$80,000 per kilometer, compared to $3,000–$8,000 in urban environments.
    • Lower ARPU Potential: Rural subscribers typically generate ARPUs of $15–$35 per month, compared to $40–$80 in urban markets, compressing the revenue available to recover infrastructure investment.

    These factors mean that fiber-to-the-home (FTTH) in rural areas often requires 15–25 years to achieve payback — far exceeding the 5–7 year investment horizons that operators and their investors demand. FWA CPE fundamentally changes this equation by eliminating the most expensive component: the physical last-mile connection.

    FWA CPE TCO Model: CAPEX and OPEX Breakdown

    A rural FWA deployment’s total cost of ownership can be modeled across four categories. The following analysis is based on a typical deployment serving 500 subscribers across a 30-kilometer radius from a single tower site:

    1. Tower and Backhaul Infrastructure (CAPEX)

    ComponentCost Range (USD)Notes
    Tower construction/co-location$15,000–$80,000Greenfield tower vs. existing structure lease
    Backhaul (microwave/fiber/satellite)$10,000–$50,000Depends on distance and terrain
    Power infrastructure (grid/solar/battery)$5,000–$25,000Solar essential for off-grid sites
    5G NR gNB (compact outdoor)$8,000–$25,000Includes baseband, radio, antenna
    Total Tower CAPEX$38,000–$180,000

    2. CPE Device Costs (CAPEX)

    CPE TypeUnit Cost (Volume)Per 500 Subs
    4G LTE Cat 12 Indoor CPE$60–$90$30,000–$45,000
    4G LTE Cat 20 Indoor CPE$90–$130$45,000–$65,000
    5G Sub-6 GHz Indoor CPE$100–$160$50,000–$80,000
    5G Sub-6 GHz Outdoor CPE$150–$250$75,000–$125,000
    5G mmWave Outdoor CPE$250–$400$125,000–$200,000

    3. Installation and Operational Costs (OPEX, Annual)

    Cost CategoryAnnual Range (USD)Per Sub/Year
    CPE installation (truck roll, mounting, activation)$25–$75 per installOne-time
    Tower site lease/power/maintenance$3,000–$8,000$6–$16
    Backhaul bandwidth (1 Gbps commit)$12,000–$36,000$24–$72
    Spectrum license fees (annualized)$2,000–$15,000$4–$30
    Network operations and support$15,000–$40,000$30–$80
    CPE management platform (TR-069/TR-369)$3,000–$10,000$6–$20
    Total Annual OPEX$35,000–$109,000$70–$218

    ROI Analysis: FWA vs. FTTH in Rural Deployments

    Let’s model a representative rural deployment of 500 subscribers with a target ARPU of $28/month. We compare three deployment scenarios:

    Metric4G FWA (Cat 20)5G FWA (Sub-6)FTTH (Rural)
    Total CAPEX (tower + CPE)$145,000$185,000$1,500,000
    Annual OPEX$55,000$65,000$40,000
    Annual Revenue (500 × $28 × 12)$168,000$168,000$168,000
    Annual Gross Margin$113,000$103,000$128,000
    Payback Period1.3 years1.8 years11.7 years
    5-Year ROI290%178%-57%

    The numbers speak for themselves. At current CPE pricing and spectrum availability, rural 4G FWA achieves payback in approximately 16 months, while 5G FWA reaches breakeven in under two years. Rural FTTH, by contrast, remains underwater even after five years at typical rural ARPU levels.

    Spectrum Strategy: Maximizing Coverage and Capacity in Rural Deployments

    Spectrum selection is the single most impactful decision in rural FWA planning. Key considerations for 2026 deployments:

    • Sub-1 GHz Bands (600/700/850 MHz): Maximum coverage radius (10–30 km per sector), ideal for low-density rural areas. Throughput limited to 20–50 Mbps per subscriber with 10–20 MHz of spectrum. Best suited for basic broadband (browsing, streaming, VoIP).
    • Mid-Band (1.8/2.1/2.6 GHz): Balanced coverage (5–15 km) and capacity (30–100 Mbps per subscriber). The sweet spot for most rural deployments, offering sufficient throughput for HD streaming, video conferencing, and cloud applications.
    • C-Band / n77/n78 (3.3–4.2 GHz): Higher capacity (50–200+ Mbps) with reduced coverage (3–8 km). Suitable for rural towns and village centers where subscriber density supports the infrastructure investment.
    • CBRS (3.5 GHz, US-specific): The shared spectrum model enables rural ISPs and WISPs to deploy private LTE/5G networks without costly spectrum auctions. CBRS SAS (Spectrum Access System) management costs approximately $2–$5 per CPE per year.

    CPE Selection Criteria for Rural Deployments

    Rural FWA CPE devices must meet a distinct set of requirements compared to urban deployments. Key selection criteria include:

    • High-Gain Antenna Support: Rural CPE should support external antenna connections (TS-9 or SMA) for high-gain directional or panel antennas (8–14 dBi), enabling reliable connectivity at cell-edge distances of 15–30 km.
    • Outdoor-Rated Design: IP65 minimum; IP67 preferred for exposed installations. Operating temperature range of -20°C to +55°C to handle seasonal extremes.
    • Power over Ethernet (PoE): Simplifies installation by combining power and data over a single Ethernet cable, reducing the need for outdoor electrical work.
    • Carrier Aggregation: Support for at least 3CA (3-carrier aggregation) on 4G, and 100 MHz CA on 5G NR, to maximize throughput from available spectrum fragments.
    • Remote Management: TR-069 or TR-369 USP support for zero-touch provisioning, remote firmware updates, and performance monitoring — critical when truck rolls cost $50–$150 in rural areas.
    • Wi-Fi 6 Integrated AP: Built-in Wi-Fi 6 (802.11ax) access point with at least 2×2 MIMO ensures the CPE doubles as the subscriber’s home gateway, eliminating the need for a separate router.

    Case Study: WISP Achieves 14-Month Payback with 4G FWA in Rural Midwest USA

    A regional WISP serving three rural counties in the US Midwest deployed CBRS-based 4G LTE FWA using Cat 20 outdoor CPE devices to connect 1,200 subscribers across 12 tower sites in 2025. Key outcomes through mid-2026:

    • Total CAPEX: $420,000 ($35,000 per tower site, including CPE)
    • Average throughput delivered: 55 Mbps down / 15 Mbps up
    • Average ARPU: $45/month (residential) + $89/month (business)
    • Subscriber acquisition cost: $185 (CPE + installation)
    • Annual revenue (Year 1): $648,000
    • Annual OPEX (Year 1): $156,000
    • Payback period: 14 months
    • Churn rate: 8% annually (vs. 25%+ for GEO satellite competitors)

    The WISP is now expanding to 5G FWA in three higher-density rural towns using C-band spectrum, targeting 2,000 additional subscribers by end of 2027.

    Government Funding and Universal Service: Unlocking Rural FWA Investment

    A critical factor improving rural FWA economics in 2026 is the availability of government subsidy programs. Operators should actively pursue these funding sources to reduce upfront CAPEX and accelerate ROI:

    • US: FCC Rural Digital Opportunity Fund (RDOF): $20.4 billion allocated through 2030, with FWA-eligible census blocks receiving up to $2,000 per location.
    • EU: Connecting Europe Broadband Fund (CEBF): €2.5 billion for rural broadband, with FWA recognized as a qualifying technology under updated 2026 guidelines.
    • India: BharatNet Phase III: $8.5 billion allocated, with FWA explicitly included as a last-mile technology option for gram panchayats.
    • Africa: World Bank Digital Economy Initiative: $5 billion for sub-Saharan Africa broadband, with FWA and satellite-backhaul combinations prioritized for rural connectivity.
    • LATAM: IDB Connect 2026: $3.2 billion for rural digital inclusion across Latin America and the Caribbean.

    Conclusion: FWA CPE Is the Economic Engine of Rural Broadband

    The economics of rural broadband have fundamentally shifted. With 4G LTE Cat 20 CPE available at $90–$130 per unit, 5G Sub-6 GHz CPE at $100–$160, and tower infrastructure CAPEX declining as equipment vendors offer compact, integrated solutions, FWA now delivers the most compelling ROI of any rural last-mile technology.

    For ISPs and MNOs evaluating rural expansion strategies in 2026, the decision framework is clear: FWA CPE provides 12–24 month payback periods, operational flexibility, and the ability to scale capacity incrementally as demand grows. Combined with government universal service funding, rural FWA is not merely viable — it is one of the most attractive growth opportunities in the telecom sector today.

    For operators seeking CPE solutions optimized for rural FWA deployments — including outdoor-rated devices with high-gain antenna support, TR-369 remote management, and multi-band carrier aggregation — Honlly Telecom offers a comprehensive portfolio of 4G and 5G FWA CPE designed for challenging deployment environments.
  • Rural Broadband Economics: The ROI Case for 4G/5G FWA CPE in Underserved Regions — A 2026 Operator Guide

    Connecting underserved rural regions remains one of the telecommunications industry’s most persistent challenges — and its largest untapped growth opportunity. With over 2.7 billion people worldwide still lacking reliable internet access, and government universal service funds (USF) allocating an estimated $45 billion globally for rural connectivity in 2026, the business case for rural broadband has never been stronger. At the center of this opportunity lies a technology that is reshaping the economics of last-mile connectivity: 4G and 5G Fixed Wireless Access (FWA) CPE.

    This guide provides ISP and MNO planning teams with a comprehensive framework for evaluating the ROI of rural FWA CPE deployments. We examine the total cost of ownership (TCO) model, per-subscriber economics, spectrum selection strategies, CPE procurement best practices, and real-world operator case studies that demonstrate how FWA is delivering profitable rural broadband services in 2026.

    The Rural Broadband Economics Gap: Why Traditional Models Fail

    Traditional wireline broadband deployment economics break down in rural areas due to three fundamental cost drivers:

    • Low Subscriber Density: Rural areas typically have 5–50 households per square kilometer, compared to 500–5,000 in urban areas. The cost of trenching fiber, erecting poles, and installing last-mile connections must be amortized across far fewer subscribers.
    • High Civil Works Costs: Fiber deployment in rural terrain — crossing rivers, navigating mountains, traversing agricultural land — costs $15,000–$80,000 per kilometer, compared to $3,000–$8,000 in urban environments.
    • Lower ARPU Potential: Rural subscribers typically generate ARPUs of $15–$35 per month, compared to $40–$80 in urban markets, compressing the revenue available to recover infrastructure investment.

    These factors mean that fiber-to-the-home (FTTH) in rural areas often requires 15–25 years to achieve payback — far exceeding the 5–7 year investment horizons that operators and their investors demand. FWA CPE fundamentally changes this equation by eliminating the most expensive component: the physical last-mile connection.

    FWA CPE TCO Model: CAPEX and OPEX Breakdown

    A rural FWA deployment’s total cost of ownership can be modeled across four categories. The following analysis is based on a typical deployment serving 500 subscribers across a 30-kilometer radius from a single tower site:

    1. Tower and Backhaul Infrastructure (CAPEX)

    ComponentCost Range (USD)Notes
    Tower construction/co-location$15,000–$80,000Greenfield tower vs. existing structure lease
    Backhaul (microwave/fiber/satellite)$10,000–$50,000Depends on distance and terrain
    Power infrastructure (grid/solar/battery)$5,000–$25,000Solar essential for off-grid sites
    5G NR gNB (compact outdoor)$8,000–$25,000Includes baseband, radio, antenna
    Total Tower CAPEX$38,000–$180,000

    2. CPE Device Costs (CAPEX)

    CPE TypeUnit Cost (Volume)Per 500 Subs
    4G LTE Cat 12 Indoor CPE$60–$90$30,000–$45,000
    4G LTE Cat 20 Indoor CPE$90–$130$45,000–$65,000
    5G Sub-6 GHz Indoor CPE$100–$160$50,000–$80,000
    5G Sub-6 GHz Outdoor CPE$150–$250$75,000–$125,000
    5G mmWave Outdoor CPE$250–$400$125,000–$200,000

    3. Installation and Operational Costs (OPEX, Annual)

    Cost CategoryAnnual Range (USD)Per Sub/Year
    CPE installation (truck roll, mounting, activation)$25–$75 per installOne-time
    Tower site lease/power/maintenance$3,000–$8,000$6–$16
    Backhaul bandwidth (1 Gbps commit)$12,000–$36,000$24–$72
    Spectrum license fees (annualized)$2,000–$15,000$4–$30
    Network operations and support$15,000–$40,000$30–$80
    CPE management platform (TR-069/TR-369)$3,000–$10,000$6–$20
    Total Annual OPEX$35,000–$109,000$70–$218

    ROI Analysis: FWA vs. FTTH in Rural Deployments

    Let’s model a representative rural deployment of 500 subscribers with a target ARPU of $28/month. We compare three deployment scenarios:

    Metric4G FWA (Cat 20)5G FWA (Sub-6)FTTH (Rural)
    Total CAPEX (tower + CPE)$145,000$185,000$1,500,000
    Annual OPEX$55,000$65,000$40,000
    Annual Revenue (500 × $28 × 12)$168,000$168,000$168,000
    Annual Gross Margin$113,000$103,000$128,000
    Payback Period1.3 years1.8 years11.7 years
    5-Year ROI290%178%-57%

    The numbers speak for themselves. At current CPE pricing and spectrum availability, rural 4G FWA achieves payback in approximately 16 months, while 5G FWA reaches breakeven in under two years. Rural FTTH, by contrast, remains underwater even after five years at typical rural ARPU levels.

    Spectrum Strategy: Maximizing Coverage and Capacity in Rural Deployments

    Spectrum selection is the single most impactful decision in rural FWA planning. Key considerations for 2026 deployments:

    • Sub-1 GHz Bands (600/700/850 MHz): Maximum coverage radius (10–30 km per sector), ideal for low-density rural areas. Throughput limited to 20–50 Mbps per subscriber with 10–20 MHz of spectrum. Best suited for basic broadband (browsing, streaming, VoIP).
    • Mid-Band (1.8/2.1/2.6 GHz): Balanced coverage (5–15 km) and capacity (30–100 Mbps per subscriber). The sweet spot for most rural deployments, offering sufficient throughput for HD streaming, video conferencing, and cloud applications.
    • C-Band / n77/n78 (3.3–4.2 GHz): Higher capacity (50–200+ Mbps) with reduced coverage (3–8 km). Suitable for rural towns and village centers where subscriber density supports the infrastructure investment.
    • CBRS (3.5 GHz, US-specific): The shared spectrum model enables rural ISPs and WISPs to deploy private LTE/5G networks without costly spectrum auctions. CBRS SAS (Spectrum Access System) management costs approximately $2–$5 per CPE per year.

    CPE Selection Criteria for Rural Deployments

    Rural FWA CPE devices must meet a distinct set of requirements compared to urban deployments. Key selection criteria include:

    • High-Gain Antenna Support: Rural CPE should support external antenna connections (TS-9 or SMA) for high-gain directional or panel antennas (8–14 dBi), enabling reliable connectivity at cell-edge distances of 15–30 km.
    • Outdoor-Rated Design: IP65 minimum; IP67 preferred for exposed installations. Operating temperature range of -20°C to +55°C to handle seasonal extremes.
    • Power over Ethernet (PoE): Simplifies installation by combining power and data over a single Ethernet cable, reducing the need for outdoor electrical work.
    • Carrier Aggregation: Support for at least 3CA (3-carrier aggregation) on 4G, and 100 MHz CA on 5G NR, to maximize throughput from available spectrum fragments.
    • Remote Management: TR-069 or TR-369 USP support for zero-touch provisioning, remote firmware updates, and performance monitoring — critical when truck rolls cost $50–$150 in rural areas.
    • Wi-Fi 6 Integrated AP: Built-in Wi-Fi 6 (802.11ax) access point with at least 2×2 MIMO ensures the CPE doubles as the subscriber’s home gateway, eliminating the need for a separate router.

    Case Study: WISP Achieves 14-Month Payback with 4G FWA in Rural Midwest USA

    A regional WISP serving three rural counties in the US Midwest deployed CBRS-based 4G LTE FWA using Cat 20 outdoor CPE devices to connect 1,200 subscribers across 12 tower sites in 2025. Key outcomes through mid-2026:

    • Total CAPEX: $420,000 ($35,000 per tower site, including CPE)
    • Average throughput delivered: 55 Mbps down / 15 Mbps up
    • Average ARPU: $45/month (residential) + $89/month (business)
    • Subscriber acquisition cost: $185 (CPE + installation)
    • Annual revenue (Year 1): $648,000
    • Annual OPEX (Year 1): $156,000
    • Payback period: 14 months
    • Churn rate: 8% annually (vs. 25%+ for GEO satellite competitors)

    The WISP is now expanding to 5G FWA in three higher-density rural towns using C-band spectrum, targeting 2,000 additional subscribers by end of 2027.

    Government Funding and Universal Service: Unlocking Rural FWA Investment

    A critical factor improving rural FWA economics in 2026 is the availability of government subsidy programs. Operators should actively pursue these funding sources to reduce upfront CAPEX and accelerate ROI:

    • US: FCC Rural Digital Opportunity Fund (RDOF): $20.4 billion allocated through 2030, with FWA-eligible census blocks receiving up to $2,000 per location.
    • EU: Connecting Europe Broadband Fund (CEBF): €2.5 billion for rural broadband, with FWA recognized as a qualifying technology under updated 2026 guidelines.
    • India: BharatNet Phase III: $8.5 billion allocated, with FWA explicitly included as a last-mile technology option for gram panchayats.
    • Africa: World Bank Digital Economy Initiative: $5 billion for sub-Saharan Africa broadband, with FWA and satellite-backhaul combinations prioritized for rural connectivity.
    • LATAM: IDB Connect 2026: $3.2 billion for rural digital inclusion across Latin America and the Caribbean.

    Conclusion: FWA CPE Is the Economic Engine of Rural Broadband

    The economics of rural broadband have fundamentally shifted. With 4G LTE Cat 20 CPE available at $90–$130 per unit, 5G Sub-6 GHz CPE at $100–$160, and tower infrastructure CAPEX declining as equipment vendors offer compact, integrated solutions, FWA now delivers the most compelling ROI of any rural last-mile technology.

    For ISPs and MNOs evaluating rural expansion strategies in 2026, the decision framework is clear: FWA CPE provides 12–24 month payback periods, operational flexibility, and the ability to scale capacity incrementally as demand grows. Combined with government universal service funding, rural FWA is not merely viable — it is one of the most attractive growth opportunities in the telecom sector today.

    For operators seeking CPE solutions optimized for rural FWA deployments — including outdoor-rated devices with high-gain antenna support, TR-369 remote management, and multi-band carrier aggregation — Honlly Telecom offers a comprehensive portfolio of 4G and 5G FWA CPE designed for challenging deployment environments.
  • Satellite-Backhaul 5G FWA CPE Deployments Expand Remote Connectivity Across APAC and LATAM Markets in H2 2026

    Satellite-Backhaul 5G FWA CPE Deployments Expand Remote Connectivity Across APAC and LATAM Markets in H2 2026

    The second half of 2026 marks a pivotal inflection point for satellite-backhaul 5G FWA (Fixed Wireless Access) CPE deployments. As LEO constellations from Starlink, OneWeb, and Project Kuiper reach operational maturity, and MEO/GEO operators expand throughput capacity, mobile network operators (MNOs) and ISPs across Asia-Pacific and Latin America are combining satellite backhaul with 5G NR last-mile CPE to extend broadband coverage into regions where fiber deployment remains economically unviable.

    This convergence of satellite bandwidth and 5G CPE technology is reshaping the economics of rural and remote connectivity. According to industry data from the GSMA and ITU, over 400 million people in APAC and LATAM still lack access to reliable broadband. Satellite-backhaul 5G FWA is emerging as the most cost-effective solution to close this gap — delivering 50–150 Mbps per household at a fraction of the cost of trenching fiber across mountainous terrain, dense jungle, or island archipelagos.

    The Technology Architecture: How Satellite-Backhaul 5G FWA Works

    In a satellite-backhaul 5G FWA deployment, the connectivity chain consists of four primary components: (1) a satellite gateway earth station that connects to the LEO/MEO/GEO constellation, (2) the satellite backhaul link providing 100 Mbps to 1 Gbps aggregate capacity to a remote tower site, (3) a 5G NR gNB base station (typically a small cell or compact outdoor unit) co-located at the tower, and (4) 5G FWA CPE devices installed at end-user premises — homes, farms, mining camps, schools, or enterprise branch offices.

    The 5G CPE plays a critical role in this architecture. Unlike urban deployments where CPE devices benefit from dense macro networks, satellite-backhaul CPE must handle higher latency (25–60 ms for LEO, 100–600 ms for GEO), potential jitter from atmospheric conditions, and the need for efficient spectrum utilization in often-contested frequency bands. Modern satellite-optimized 5G CPE devices incorporate several key capabilities:

    • TCP Acceleration and PEP (Performance Enhancing Proxy) Support: On-device TCP optimization mitigates the throughput degradation that standard TCP congestion control algorithms experience over satellite links.
    • Adaptive Modulation and Coding (AMC): The CPE dynamically adjusts modulation schemes (QPSK through 256QAM) based on real-time link conditions, maintaining stable connections through rain fade and atmospheric attenuation.
    • Multi-Band Carrier Aggregation: Support for n77, n78, n79, and n41 bands with carrier aggregation ensures sufficient spectral efficiency to maximize the satellite backhaul pipe.
    • Edge Caching and Local Breakout: Integrated edge compute capabilities cache frequently accessed content locally, reducing round-trip satellite latency for common applications.
    • Dual-SIM / Multi-IMSI: In multi-operator environments, the CPE can fall back to terrestrial backhaul when available, ensuring service continuity.

    APAC Deployments: Island Nations and Mountain Communities Lead Adoption

    Asia-Pacific is the world’s largest and most diverse FWA market, and satellite-backhaul 5G CPE is gaining traction across three distinct deployment scenarios:

    Indonesia and the Philippines — Archipelagic Connectivity: With over 17,000 and 7,600 islands respectively, these nations face unique infrastructure challenges. Indonesian operator Telkomsel has deployed over 1,200 satellite-backhaul 5G FWA sites across Sulawesi, Papua, and Nusa Tenggara in 2026, using a combination of Starlink Business backhaul and 5G NR CPE in the 3.5 GHz band. Each site serves 50–200 households with 30–80 Mbps plans, priced competitively against existing GEO satellite broadband offerings.

    Nepal and Bhutan — Mountain Terrain Deployments: In the Himalayas, where fiber installation costs can exceed $80,000 per kilometer, Nepali ISP Vianet and Bhutan Telecom have piloted satellite-backhaul 5G FWA using compact outdoor CPE units with high-gain directional antennas. These deployments leverage OneWeb’s LEO constellation for backhaul and operate 5G NR in the n78 band at 3.5 GHz. The CPE devices are ruggedized for extreme weather conditions, with operating temperature ranges from -30°C to +55°C and IP67-rated enclosures.

    Australia — Mining and Agricultural Connectivity: Rio Tinto and BHP have deployed private 5G networks at remote mine sites in Western Australia’s Pilbara region, using satellite backhaul to connect to corporate networks in Perth. The 5G CPE devices serve as the last-mile link for autonomous haul trucks, remote operations centers, and worker accommodation connectivity.

    LATAM Market: Bridging the Andean and Amazonian Digital Divide

    Latin America presents a different set of challenges — vast Amazonian territories, Andean mountain communities, and underserved rural populations spread across challenging topography. In 2026, satellite-backhaul 5G FWA deployments are accelerating across the region:

    Brazil — Amazon Connectivity Program: Under the Brazilian government’s Norte Conectado program, TIM Brasil and Claro have deployed satellite-backhaul 5G FWA in over 80 Amazon riverside communities. Using SES’s O3b mPOWER MEO constellation for backhaul and 5G CPE operating in the 3.5 GHz band, these deployments deliver 25–100 Mbps to schools, health clinics, and community centers. The CPE devices feature integrated Wi-Fi 6 access points, allowing each installation to serve as a community hotspot.

    Chile and Peru — Andean Connectivity: Entel Chile has partnered with Starlink to deploy satellite-backhaul 5G FWA in the Andean highlands, serving mining operations and remote communities above 4,000 meters elevation. The CPE devices are specially engineered for high-altitude operation, with enhanced thermal management and radiation-hardened components to withstand increased cosmic radiation exposure at altitude.

    Colombia — Rural Education Connectivity: The Colombian Ministry of ICT’s Conectividad para la Educación program has connected over 5,000 rural schools using satellite-backhaul 5G FWA CPE. Each school installation includes a solar-powered outdoor CPE unit with battery backup, delivering 20–50 Mbps for e-learning platforms and digital literacy programs.

    Economic Model: When Satellite-Backhaul 5G FWA Beats Fiber

    The economic case for satellite-backhaul 5G FWA becomes compelling when comparing total cost of ownership (TCO) against fiber deployment in remote areas. A typical satellite-backhaul 5G FWA site covering 100–200 households requires a capital expenditure of $25,000–$60,000, inclusive of satellite terminal, 5G gNB, tower infrastructure, solar power system, and CPE devices. The equivalent fiber build-out over 20–50 kilometers of challenging terrain would cost $400,000–$2,000,000 — a 10x to 40x difference.

    Monthly operational costs for satellite backhaul are also declining. LEO capacity pricing has dropped below $50 per Mbps per month in many regions, down from over $200 in 2023. When combined with the declining cost of 5G CPE devices — now available at $80–$150 per unit in volume — the per-subscriber economics support ARPUs as low as $15–$25 per month, making satellite-backhaul 5G FWA viable even in lower-income rural markets.

    CPE Requirements for Satellite-Backhaul 5G FWA: What B2B Buyers Should Look For

    For operators and ISPs procuring CPE for satellite-backhaul deployments, several specifications are critical beyond standard 5G FWA requirements:

    • Latency Tolerance and Buffer Management: CPE devices must support large buffer sizes (1–5 MB per bearer) and latency-aware scheduling to maintain throughput over 25–600 ms backhaul links without TCP collapse.
    • Outdoor-Rated Design with Integrated Antenna: IP67 or higher enclosure rating, integrated high-gain (8–12 dBi) directional or panel antennas, and wind-load ratings suitable for tower/mast mounting.
    • Remote Management via TR-369 USP: Full USP (User Services Platform) agent support for remote provisioning, firmware updates, performance monitoring, and fault diagnostics — critical when sites are hundreds of kilometers from the nearest technician.
    • Power Flexibility: Support for PoE (Power over Ethernet), DC input (12–48V), and solar/battery integration, with typical power consumption below 15W to minimize solar panel sizing requirements.
    • Multi-WAN Failover: Built-in Ethernet WAN port for terrestrial backhaul fallback, with automatic failover when fiber or microwave becomes available.

    Outlook: 2026–2028

    As LEO constellation density increases — Starlink’s Gen2 constellation alone targets over 30,000 satellites — and 5G CPE costs continue their downward trajectory, satellite-backhaul FWA is poised to become the dominant connectivity model for remote and rural broadband. The GSMA projects that satellite-integrated 5G FWA connections will exceed 80 million globally by 2028, with APAC and LATAM accounting for over 60% of deployments.

    For B2B buyers — MNOs, ISPs, rural broadband providers, mining operators, agricultural enterprises, and government connectivity programs — the message is clear: satellite-backhaul 5G FWA CPE is no longer a niche solution. It is a mature, cost-effective, and rapidly scaling technology platform that can connect the unconnected, unlock economic development in remote regions, and deliver measurable ROI within 12–24 months of deployment.

  • Rural Broadband Economics: The ROI Case for 4G/5G FWA CPE in Underserved Regions — A 2026 Operator Guide

    Connecting underserved rural regions remains one of the telecommunications industry’s most persistent challenges — and its largest untapped growth opportunity. With over 2.7 billion people worldwide still lacking reliable internet access, and government universal service funds (USF) allocating an estimated $45 billion globally for rural connectivity in 2026, the business case for rural broadband has never been stronger. At the center of this opportunity lies a technology that is reshaping the economics of last-mile connectivity: 4G and 5G Fixed Wireless Access (FWA) CPE.

    This guide provides ISP and MNO planning teams with a comprehensive framework for evaluating the ROI of rural FWA CPE deployments. We examine the total cost of ownership (TCO) model, per-subscriber economics, spectrum selection strategies, CPE procurement best practices, and real-world operator case studies that demonstrate how FWA is delivering profitable rural broadband services in 2026.

    The Rural Broadband Economics Gap: Why Traditional Models Fail

    Traditional wireline broadband deployment economics break down in rural areas due to three fundamental cost drivers:

    • Low Subscriber Density: Rural areas typically have 5–50 households per square kilometer, compared to 500–5,000 in urban areas. The cost of trenching fiber, erecting poles, and installing last-mile connections must be amortized across far fewer subscribers.
    • High Civil Works Costs: Fiber deployment in rural terrain — crossing rivers, navigating mountains, traversing agricultural land — costs $15,000–$80,000 per kilometer, compared to $3,000–$8,000 in urban environments.
    • Lower ARPU Potential: Rural subscribers typically generate ARPUs of $15–$35 per month, compared to $40–$80 in urban markets, compressing the revenue available to recover infrastructure investment.

    These factors mean that fiber-to-the-home (FTTH) in rural areas often requires 15–25 years to achieve payback — far exceeding the 5–7 year investment horizons that operators and their investors demand. FWA CPE fundamentally changes this equation by eliminating the most expensive component: the physical last-mile connection.

    FWA CPE TCO Model: CAPEX and OPEX Breakdown

    A rural FWA deployment’s total cost of ownership can be modeled across four categories. The following analysis is based on a typical deployment serving 500 subscribers across a 30-kilometer radius from a single tower site:

    1. Tower and Backhaul Infrastructure (CAPEX)

    ComponentCost Range (USD)Notes
    Tower construction/co-location$15,000–$80,000Greenfield tower vs. existing structure lease
    Backhaul (microwave/fiber/satellite)$10,000–$50,000Depends on distance and terrain
    Power infrastructure (grid/solar/battery)$5,000–$25,000Solar essential for off-grid sites
    5G NR gNB (compact outdoor)$8,000–$25,000Includes baseband, radio, antenna
    Total Tower CAPEX$38,000–$180,000

    2. CPE Device Costs (CAPEX)

    CPE TypeUnit Cost (Volume)Per 500 Subs
    4G LTE Cat 12 Indoor CPE$60–$90$30,000–$45,000
    4G LTE Cat 20 Indoor CPE$90–$130$45,000–$65,000
    5G Sub-6 GHz Indoor CPE$100–$160$50,000–$80,000
    5G Sub-6 GHz Outdoor CPE$150–$250$75,000–$125,000
    5G mmWave Outdoor CPE$250–$400$125,000–$200,000

    3. Installation and Operational Costs (OPEX, Annual)

    Cost CategoryAnnual Range (USD)Per Sub/Year
    CPE installation (truck roll, mounting, activation)$25–$75 per installOne-time
    Tower site lease/power/maintenance$3,000–$8,000$6–$16
    Backhaul bandwidth (1 Gbps commit)$12,000–$36,000$24–$72
    Spectrum license fees (annualized)$2,000–$15,000$4–$30
    Network operations and support$15,000–$40,000$30–$80
    CPE management platform (TR-069/TR-369)$3,000–$10,000$6–$20
    Total Annual OPEX$35,000–$109,000$70–$218

    ROI Analysis: FWA vs. FTTH in Rural Deployments

    Let’s model a representative rural deployment of 500 subscribers with a target ARPU of $28/month. We compare three deployment scenarios:

    Metric4G FWA (Cat 20)5G FWA (Sub-6)FTTH (Rural)
    Total CAPEX (tower + CPE)$145,000$185,000$1,500,000
    Annual OPEX$55,000$65,000$40,000
    Annual Revenue (500 × $28 × 12)$168,000$168,000$168,000
    Annual Gross Margin$113,000$103,000$128,000
    Payback Period1.3 years1.8 years11.7 years
    5-Year ROI290%178%-57%

    The numbers speak for themselves. At current CPE pricing and spectrum availability, rural 4G FWA achieves payback in approximately 16 months, while 5G FWA reaches breakeven in under two years. Rural FTTH, by contrast, remains underwater even after five years at typical rural ARPU levels.

    Spectrum Strategy: Maximizing Coverage and Capacity in Rural Deployments

    Spectrum selection is the single most impactful decision in rural FWA planning. Key considerations for 2026 deployments:

    • Sub-1 GHz Bands (600/700/850 MHz): Maximum coverage radius (10–30 km per sector), ideal for low-density rural areas. Throughput limited to 20–50 Mbps per subscriber with 10–20 MHz of spectrum. Best suited for basic broadband (browsing, streaming, VoIP).
    • Mid-Band (1.8/2.1/2.6 GHz): Balanced coverage (5–15 km) and capacity (30–100 Mbps per subscriber). The sweet spot for most rural deployments, offering sufficient throughput for HD streaming, video conferencing, and cloud applications.
    • C-Band / n77/n78 (3.3–4.2 GHz): Higher capacity (50–200+ Mbps) with reduced coverage (3–8 km). Suitable for rural towns and village centers where subscriber density supports the infrastructure investment.
    • CBRS (3.5 GHz, US-specific): The shared spectrum model enables rural ISPs and WISPs to deploy private LTE/5G networks without costly spectrum auctions. CBRS SAS (Spectrum Access System) management costs approximately $2–$5 per CPE per year.

    CPE Selection Criteria for Rural Deployments

    Rural FWA CPE devices must meet a distinct set of requirements compared to urban deployments. Key selection criteria include:

    • High-Gain Antenna Support: Rural CPE should support external antenna connections (TS-9 or SMA) for high-gain directional or panel antennas (8–14 dBi), enabling reliable connectivity at cell-edge distances of 15–30 km.
    • Outdoor-Rated Design: IP65 minimum; IP67 preferred for exposed installations. Operating temperature range of -20°C to +55°C to handle seasonal extremes.
    • Power over Ethernet (PoE): Simplifies installation by combining power and data over a single Ethernet cable, reducing the need for outdoor electrical work.
    • Carrier Aggregation: Support for at least 3CA (3-carrier aggregation) on 4G, and 100 MHz CA on 5G NR, to maximize throughput from available spectrum fragments.
    • Remote Management: TR-069 or TR-369 USP support for zero-touch provisioning, remote firmware updates, and performance monitoring — critical when truck rolls cost $50–$150 in rural areas.
    • Wi-Fi 6 Integrated AP: Built-in Wi-Fi 6 (802.11ax) access point with at least 2×2 MIMO ensures the CPE doubles as the subscriber’s home gateway, eliminating the need for a separate router.

    Case Study: WISP Achieves 14-Month Payback with 4G FWA in Rural Midwest USA

    A regional WISP serving three rural counties in the US Midwest deployed CBRS-based 4G LTE FWA using Cat 20 outdoor CPE devices to connect 1,200 subscribers across 12 tower sites in 2025. Key outcomes through mid-2026:

    • Total CAPEX: $420,000 ($35,000 per tower site, including CPE)
    • Average throughput delivered: 55 Mbps down / 15 Mbps up
    • Average ARPU: $45/month (residential) + $89/month (business)
    • Subscriber acquisition cost: $185 (CPE + installation)
    • Annual revenue (Year 1): $648,000
    • Annual OPEX (Year 1): $156,000
    • Payback period: 14 months
    • Churn rate: 8% annually (vs. 25%+ for GEO satellite competitors)

    The WISP is now expanding to 5G FWA in three higher-density rural towns using C-band spectrum, targeting 2,000 additional subscribers by end of 2027.

    Government Funding and Universal Service: Unlocking Rural FWA Investment

    A critical factor improving rural FWA economics in 2026 is the availability of government subsidy programs. Operators should actively pursue these funding sources to reduce upfront CAPEX and accelerate ROI:

    • US: FCC Rural Digital Opportunity Fund (RDOF): $20.4 billion allocated through 2030, with FWA-eligible census blocks receiving up to $2,000 per location.
    • EU: Connecting Europe Broadband Fund (CEBF): €2.5 billion for rural broadband, with FWA recognized as a qualifying technology under updated 2026 guidelines.
    • India: BharatNet Phase III: $8.5 billion allocated, with FWA explicitly included as a last-mile technology option for gram panchayats.
    • Africa: World Bank Digital Economy Initiative: $5 billion for sub-Saharan Africa broadband, with FWA and satellite-backhaul combinations prioritized for rural connectivity.
    • LATAM: IDB Connect 2026: $3.2 billion for rural digital inclusion across Latin America and the Caribbean.

    Conclusion: FWA CPE Is the Economic Engine of Rural Broadband

    The economics of rural broadband have fundamentally shifted. With 4G LTE Cat 20 CPE available at $90–$130 per unit, 5G Sub-6 GHz CPE at $100–$160, and tower infrastructure CAPEX declining as equipment vendors offer compact, integrated solutions, FWA now delivers the most compelling ROI of any rural last-mile technology.

    For ISPs and MNOs evaluating rural expansion strategies in 2026, the decision framework is clear: FWA CPE provides 12–24 month payback periods, operational flexibility, and the ability to scale capacity incrementally as demand grows. Combined with government universal service funding, rural FWA is not merely viable — it is one of the most attractive growth opportunities in the telecom sector today.

    For operators seeking CPE solutions optimized for rural FWA deployments — including outdoor-rated devices with high-gain antenna support, TR-369 remote management, and multi-band carrier aggregation — Honlly Telecom offers a comprehensive portfolio of 4G and 5G FWA CPE designed for challenging deployment environments.
  • Satellite-Backhaul 5G FWA CPE Deployments Expand Remote Connectivity Across APAC and LATAM Markets in H2 2026

    The second half of 2026 marks a pivotal inflection point for satellite-backhaul 5G FWA (Fixed Wireless Access) CPE deployments. As LEO constellations from Starlink, OneWeb, and Project Kuiper reach operational maturity, and MEO/GEO operators expand throughput capacity, mobile network operators (MNOs) and ISPs across Asia-Pacific and Latin America are combining satellite backhaul with 5G NR last-mile CPE to extend broadband coverage into regions where fiber deployment remains economically unviable.

    This convergence of satellite bandwidth and 5G CPE technology is reshaping the economics of rural and remote connectivity. According to industry data from the GSMA and ITU, over 400 million people in APAC and LATAM still lack access to reliable broadband. Satellite-backhaul 5G FWA is emerging as the most cost-effective solution to close this gap — delivering 50–150 Mbps per household at a fraction of the cost of trenching fiber across mountainous terrain, dense jungle, or island archipelagos.

    The Technology Architecture: How Satellite-Backhaul 5G FWA Works

    In a satellite-backhaul 5G FWA deployment, the connectivity chain consists of four primary components: (1) a satellite gateway earth station that connects to the LEO/MEO/GEO constellation, (2) the satellite backhaul link providing 100 Mbps to 1 Gbps aggregate capacity to a remote tower site, (3) a 5G NR gNB base station (typically a small cell or compact outdoor unit) co-located at the tower, and (4) 5G FWA CPE devices installed at end-user premises — homes, farms, mining camps, schools, or enterprise branch offices.

    The 5G CPE plays a critical role in this architecture. Unlike urban deployments where CPE devices benefit from dense macro networks, satellite-backhaul CPE must handle higher latency (25–60 ms for LEO, 100–600 ms for GEO), potential jitter from atmospheric conditions, and the need for efficient spectrum utilization in often-contested frequency bands. Modern satellite-optimized 5G CPE devices incorporate several key capabilities:

    • TCP Acceleration and PEP (Performance Enhancing Proxy) Support: On-device TCP optimization mitigates the throughput degradation that standard TCP congestion control algorithms experience over satellite links.
    • Adaptive Modulation and Coding (AMC): The CPE dynamically adjusts modulation schemes (QPSK through 256QAM) based on real-time link conditions, maintaining stable connections through rain fade and atmospheric attenuation.
    • Multi-Band Carrier Aggregation: Support for n77, n78, n79, and n41 bands with carrier aggregation ensures sufficient spectral efficiency to maximize the satellite backhaul pipe.
    • Edge Caching and Local Breakout: Integrated edge compute capabilities cache frequently accessed content locally, reducing round-trip satellite latency for common applications.
    • Dual-SIM / Multi-IMSI: In multi-operator environments, the CPE can fall back to terrestrial backhaul when available, ensuring service continuity.

    APAC Deployments: Island Nations and Mountain Communities Lead Adoption

    Asia-Pacific is the world’s largest and most diverse FWA market, and satellite-backhaul 5G CPE is gaining traction across three distinct deployment scenarios:

    Indonesia and the Philippines — Archipelagic Connectivity: With over 17,000 and 7,600 islands respectively, these nations face unique infrastructure challenges. Indonesian operator Telkomsel has deployed over 1,200 satellite-backhaul 5G FWA sites across Sulawesi, Papua, and Nusa Tenggara in 2026, using a combination of Starlink Business backhaul and 5G NR CPE in the 3.5 GHz band. Each site serves 50–200 households with 30–80 Mbps plans, priced competitively against existing GEO satellite broadband offerings.

    Nepal and Bhutan — Mountain Terrain Deployments: In the Himalayas, where fiber installation costs can exceed $80,000 per kilometer, Nepali ISP Vianet and Bhutan Telecom have piloted satellite-backhaul 5G FWA using compact outdoor CPE units with high-gain directional antennas. These deployments leverage OneWeb’s LEO constellation for backhaul and operate 5G NR in the n78 band at 3.5 GHz. The CPE devices are ruggedized for extreme weather conditions, with operating temperature ranges from -30°C to +55°C and IP67-rated enclosures.

    Australia — Mining and Agricultural Connectivity: Rio Tinto and BHP have deployed private 5G networks at remote mine sites in Western Australia’s Pilbara region, using satellite backhaul to connect to corporate networks in Perth. The 5G CPE devices serve as the last-mile link for autonomous haul trucks, remote operations centers, and worker accommodation connectivity.

    LATAM Market: Bridging the Andean and Amazonian Digital Divide

    Latin America presents a different set of challenges — vast Amazonian territories, Andean mountain communities, and underserved rural populations spread across challenging topography. In 2026, satellite-backhaul 5G FWA deployments are accelerating across the region:

    Brazil — Amazon Connectivity Program: Under the Brazilian government’s Norte Conectado program, TIM Brasil and Claro have deployed satellite-backhaul 5G FWA in over 80 Amazon riverside communities. Using SES’s O3b mPOWER MEO constellation for backhaul and 5G CPE operating in the 3.5 GHz band, these deployments deliver 25–100 Mbps to schools, health clinics, and community centers. The CPE devices feature integrated Wi-Fi 6 access points, allowing each installation to serve as a community hotspot.

    Chile and Peru — Andean Connectivity: Entel Chile has partnered with Starlink to deploy satellite-backhaul 5G FWA in the Andean highlands, serving mining operations and remote communities above 4,000 meters elevation. The CPE devices are specially engineered for high-altitude operation, with enhanced thermal management and radiation-hardened components to withstand increased cosmic radiation exposure at altitude.

    Colombia — Rural Education Connectivity: The Colombian Ministry of ICT’s Conectividad para la Educación program has connected over 5,000 rural schools using satellite-backhaul 5G FWA CPE. Each school installation includes a solar-powered outdoor CPE unit with battery backup, delivering 20–50 Mbps for e-learning platforms and digital literacy programs.

    Economic Model: When Satellite-Backhaul 5G FWA Beats Fiber

    The economic case for satellite-backhaul 5G FWA becomes compelling when comparing total cost of ownership (TCO) against fiber deployment in remote areas. A typical satellite-backhaul 5G FWA site covering 100–200 households requires a capital expenditure of $25,000–$60,000, inclusive of satellite terminal, 5G gNB, tower infrastructure, solar power system, and CPE devices. The equivalent fiber build-out over 20–50 kilometers of challenging terrain would cost $400,000–$2,000,000 — a 10x to 40x difference.

    Monthly operational costs for satellite backhaul are also declining. LEO capacity pricing has dropped below $50 per Mbps per month in many regions, down from over $200 in 2023. When combined with the declining cost of 5G CPE devices — now available at $80–$150 per unit in volume — the per-subscriber economics support ARPUs as low as $15–$25 per month, making satellite-backhaul 5G FWA viable even in lower-income rural markets.

    CPE Requirements for Satellite-Backhaul 5G FWA: What B2B Buyers Should Look For

    For operators and ISPs procuring CPE for satellite-backhaul deployments, several specifications are critical beyond standard 5G FWA requirements:

    • Latency Tolerance and Buffer Management: CPE devices must support large buffer sizes (1–5 MB per bearer) and latency-aware scheduling to maintain throughput over 25–600 ms backhaul links without TCP collapse.
    • Outdoor-Rated Design with Integrated Antenna: IP67 or higher enclosure rating, integrated high-gain (8–12 dBi) directional or panel antennas, and wind-load ratings suitable for tower/mast mounting.
    • Remote Management via TR-369 USP: Full USP (User Services Platform) agent support for remote provisioning, firmware updates, performance monitoring, and fault diagnostics — critical when sites are hundreds of kilometers from the nearest technician.
    • Power Flexibility: Support for PoE (Power over Ethernet), DC input (12–48V), and solar/battery integration, with typical power consumption below 15W to minimize solar panel sizing requirements.
    • Multi-WAN Failover: Built-in Ethernet WAN port for terrestrial backhaul fallback, with automatic failover when fiber or microwave becomes available.

    Outlook: 2026–2028

    As LEO constellation density increases — Starlink’s Gen2 constellation alone targets over 30,000 satellites — and 5G CPE costs continue their downward trajectory, satellite-backhaul FWA is poised to become the dominant connectivity model for remote and rural broadband. The GSMA projects that satellite-integrated 5G FWA connections will exceed 80 million globally by 2028, with APAC and LATAM accounting for over 60% of deployments.

    For B2B buyers — MNOs, ISPs, rural broadband providers, mining operators, agricultural enterprises, and government connectivity programs — the message is clear: satellite-backhaul 5G FWA CPE is no longer a niche solution. It is a mature, cost-effective, and rapidly scaling technology platform that can connect the unconnected, unlock economic development in remote regions, and deliver measurable ROI within 12–24 months of deployment.

  • How MVNOs and ISPs Can Build a Differentiated FWA Offering with White-Label 4G/5G CPE: A Go-to-Market Guide for 2026

    How MVNOs and ISPs Can Build a Differentiated FWA Offering with White-Label 4G/5G CPE: A Go-to-Market Guide for 2026

    In an increasingly competitive fixed wireless access (FWA) market, MVNOs and regional ISPs face a fundamental challenge: how to differentiate their broadband offering when the underlying network infrastructure is often shared with larger competitors. The answer, increasingly, lies in the CPE itself. A well-chosen white-label 4G or 5G CPE strategy can transform a commodity connectivity service into a branded, differentiated, and defensible product offering — without the capital investment required to build proprietary hardware. This guide outlines the strategic and operational framework for MVNOs and ISPs to build a differentiated FWA offering using white-label CPE in 2026.

    Why White-Label CPE Matters for MVNO and ISP Strategy

    The CPE sitting in a subscriber’s home or office is the only physical touchpoint between the service provider and the end customer. It is also the most visible brand asset. When an MVNO ships a generic, unbranded router to a subscriber, the brand experience is diluted, and the subscriber’s loyalty attaches to the network — not the service provider. White-label CPE changes this equation in several critical ways:

    • Brand presence: A custom-branded CPE with the MVNO or ISP logo, custom packaging, and branded web UI creates a consistent brand experience from unboxing to daily use. This is particularly valuable for ISPs competing against incumbent operators with strong consumer brand recognition.
    • Service differentiation: White-label CPE can be pre-configured with custom firmware features — branded captive portals, value-added services (parental controls, QoS profiles, IoT network segmentation), and operator-specific cloud management dashboards — that generic CPE cannot deliver.
    • Customer retention: Subscribers using a branded, customized CPE are less likely to churn because the device is visibly associated with the provider’s service. If a subscriber switches providers, the CPE becomes a visible reminder of what they left.
    • Revenue expansion: A white-label CPE platform enables upselling of managed Wi-Fi services, enhanced security packages, and premium support tiers — revenue streams that are impossible with generic off-the-shelf routers.

    Building the White-Label CPE Strategy: A Four-Phase Framework

    Phase 1: Define Your Differentiation Layer

    Before selecting a CPE partner, MVNOs and ISPs must define exactly how the CPE will contribute to competitive differentiation. There are four primary differentiation layers:

    1. Brand identity layer: Custom industrial design (enclosure color, form factor, logo placement), branded packaging, and customized web UI. This is the minimum viable white-label approach and can be implemented within 4-8 weeks with the right OEM partner.
    2. Software experience layer: Custom firmware builds that include operator-specific features: self-installation wizard, bandwidth usage dashboard, parental controls, guest network management, and integrated billing portal access. This requires deeper OEM collaboration but delivers the highest perceived value to subscribers.
    3. Network optimization layer: Operator-specific RF calibration, band-locking profiles, carrier aggregation optimization for the MNO’s specific spectrum holdings, and APN pre-configuration. This layer directly impacts service quality and subscriber satisfaction.
    4. Cloud management layer: White-label TR-069/TR-369 ACS platform or cloud controller that provides the operator with fleet-wide CPE management, remote diagnostics, bulk firmware updates, and performance analytics — all under the operator’s brand.

    Phase 2: Select the Right OEM/ODM CPE Partner

    Choosing a white-label CPE partner is a strategic decision that affects product quality, time-to-market, and long-term operational costs. B2B buyers should evaluate potential OEM/ODM partners across these criteria:

    • Platform flexibility: Can the partner support multiple chipset platforms (Qualcomm, MediaTek, UNISOC) across LTE and 5G NR? A multi-platform partner allows the operator to source the best silicon for each market segment without switching vendors.
    • Customization depth: What is the minimum order quantity (MOQ) for custom enclosures? Can the partner support custom firmware builds, custom packaging, and regional certification (FCC, CE, GCF, PTCRB)? How long is the customization lead time?
    • Software capability: Does the partner have an in-house software engineering team that can develop custom features, integrate with the operator’s OSS/BSS, and provide ongoing firmware maintenance? Open-source CPE stacks (OpenWrt, prplOS, RDK-B) offer greater long-term flexibility than proprietary firmware.
    • Quality and reliability: Request field failure rate data, MTBF specifications, and manufacturing quality certifications (ISO 9001, ISO 14001). A CPE with a 2% annual field failure rate versus 5% represents a significant difference in truck-roll cost and subscriber churn over a 3-year deployment.
    • Logistics and fulfilment: Can the partner support drop-shipping directly to subscribers? What are the warehousing and inventory management options? Regional warehousing can reduce lead times from 6-8 weeks to 3-5 days for large operators.

    Phase 3: Develop the Service Wrapper

    The CPE is hardware; the differentiated offering is the complete service wrapper around it. MVNOs and ISPs should design these service elements in parallel with CPE selection:

    • Self-installation experience: A guided mobile app or web-based setup wizard that reduces installation truck rolls. Data from operators shows that self-installation rates of 70-85% are achievable with well-designed CPE onboarding, reducing per-subscriber acquisition cost by $80-150.
    • Tiered service plans: Use the CPE’s software capabilities to enforce bandwidth tiers, data caps, and QoS profiles that map to differentiated price points. A single CPE hardware SKU can serve multiple subscription tiers through software configuration alone.
    • Managed Wi-Fi add-on: Offer subscribers a premium managed Wi-Fi service (optimized channel selection, band steering, mesh extension) as a monthly upsell. This typically adds $3-7/month ARPU with near-zero incremental hardware cost on capable CPE platforms.
    • Business-grade SLAs: For enterprise and SMB subscribers, offer enhanced support SLAs, static IP options, VPN endpoint configuration, and priority network access — all manageable through the CPE’s cloud management platform.

    Phase 4: Launch, Measure, and Iterate

    A white-label CPE deployment is not a one-time project. Successful operators treat the CPE as a continuously evolving platform:

    • Subscriber analytics: Use telemetry from the CPE fleet to understand usage patterns, identify churn risk signals (declining signal quality, frequent reboots), and optimize network capacity planning.
    • Firmware iteration: Release quarterly firmware updates that add features, improve stability, and address security vulnerabilities. A CPE that improves over time generates positive word-of-mouth and reduces churn.
    • A/B testing: Use the CPE fleet to A/B test different QoS configurations, Wi-Fi channel strategies, and user interface designs to continuously optimize subscriber experience.
    • Expansion roadmap: Plan for the next CPE generation 12-18 months in advance. The transition from LTE to 5G, or from Wi-Fi 5 to Wi-Fi 6/6E/7, should be on the roadmap from day one with a clear hardware refresh strategy.

    The Business Case: White-Label CPE ROI

    For MVNOs and ISPs evaluating the business case, the ROI of white-label CPE can be quantified across three dimensions:

    • Churn reduction: Operators with branded CPE and custom firmware report 15-25% lower annual churn rates compared to those using generic CPE. For an ISP with 50,000 subscribers and an average acquisition cost of $200 per subscriber, a 5-percentage-point churn reduction represents approximately $5 million in annual savings.
    • ARPU uplift: Managed Wi-Fi and enhanced support tiers enabled by white-label CPE platforms typically add $3-7/month in incremental ARPU. At 50,000 subscribers with 30% adoption, this translates to $540,000-$1.26 million in annual recurring revenue.
    • Brand equity: While harder to quantify, branded CPE builds long-term brand recognition and trust that supports premium pricing, partnership leverage, and market expansion. In competitive markets, this can be the difference between a sustainable MVNO and one that competes solely on price.

    Honlly Telecom’s White-Label CPE Partnership Program

    Honlly Telecom provides comprehensive OEM/ODM white-label CPE solutions for MVNOs, ISPs, and telecom operators globally. Our partnership program includes:

    • Custom industrial design and enclosure branding with MOQs as low as 500 units
    • Custom firmware development on OpenWrt and RDK-B platforms with operator-specific feature integration
    • Regional certification support (FCC, CE, GCF, PTCRB, Anatel, NCC, and others)
    • Custom packaging, quick-start guides, and branded web UI in the operator’s language and design language
    • Cloud management platform integration with TR-069/TR-369 support
    • Flexible logistics: factory-direct shipping, regional warehousing, or drop-ship to end subscribers
    • Product portfolio spanning 4G Cat 4/6/12/20 CPE, 5G NR Sub-6 GHz and mmWave CPE, indoor and outdoor form factors, and industrial-grade routers

    To explore a white-label CPE partnership with Honlly Telecom, contact our B2B OEM/ODM team for a consultation and product roadmap discussion.

  • 4G LTE Cat 6 vs Cat 12 vs Cat 20 CPE: A Practical B2B Buyer’s Guide to Choosing the Right LTE Category for ISP and Enterprise Deployments

    4G LTE Cat 6 vs Cat 12 vs Cat 20 CPE: A Practical B2B Buyer’s Guide to Choosing the Right LTE Category for ISP and Enterprise Deployments

    For ISPs, MVNOs, and enterprise buyers deploying LTE-based fixed wireless access or backup connectivity, the choice between 4G LTE Cat 6, Cat 12, and Cat 20 CPE is one of the most consequential procurement decisions. While 5G dominates industry headlines, 4G LTE remains the workhorse of global wireless broadband — particularly in markets where 5G coverage is still expanding, spectrum costs are constrained, or deployment economics favor LTE. This guide provides a practical, technically grounded comparison to help B2B buyers select the right LTE category for their specific deployment requirements.

    Understanding LTE UE Categories: What the Numbers Mean

    LTE User Equipment (UE) categories are defined by 3GPP and specify the maximum theoretical downlink and uplink data rates a device can achieve. The category number is not a marketing label — it directly corresponds to specific technical capabilities including carrier aggregation (CA) configuration, MIMO layers, and modulation scheme:

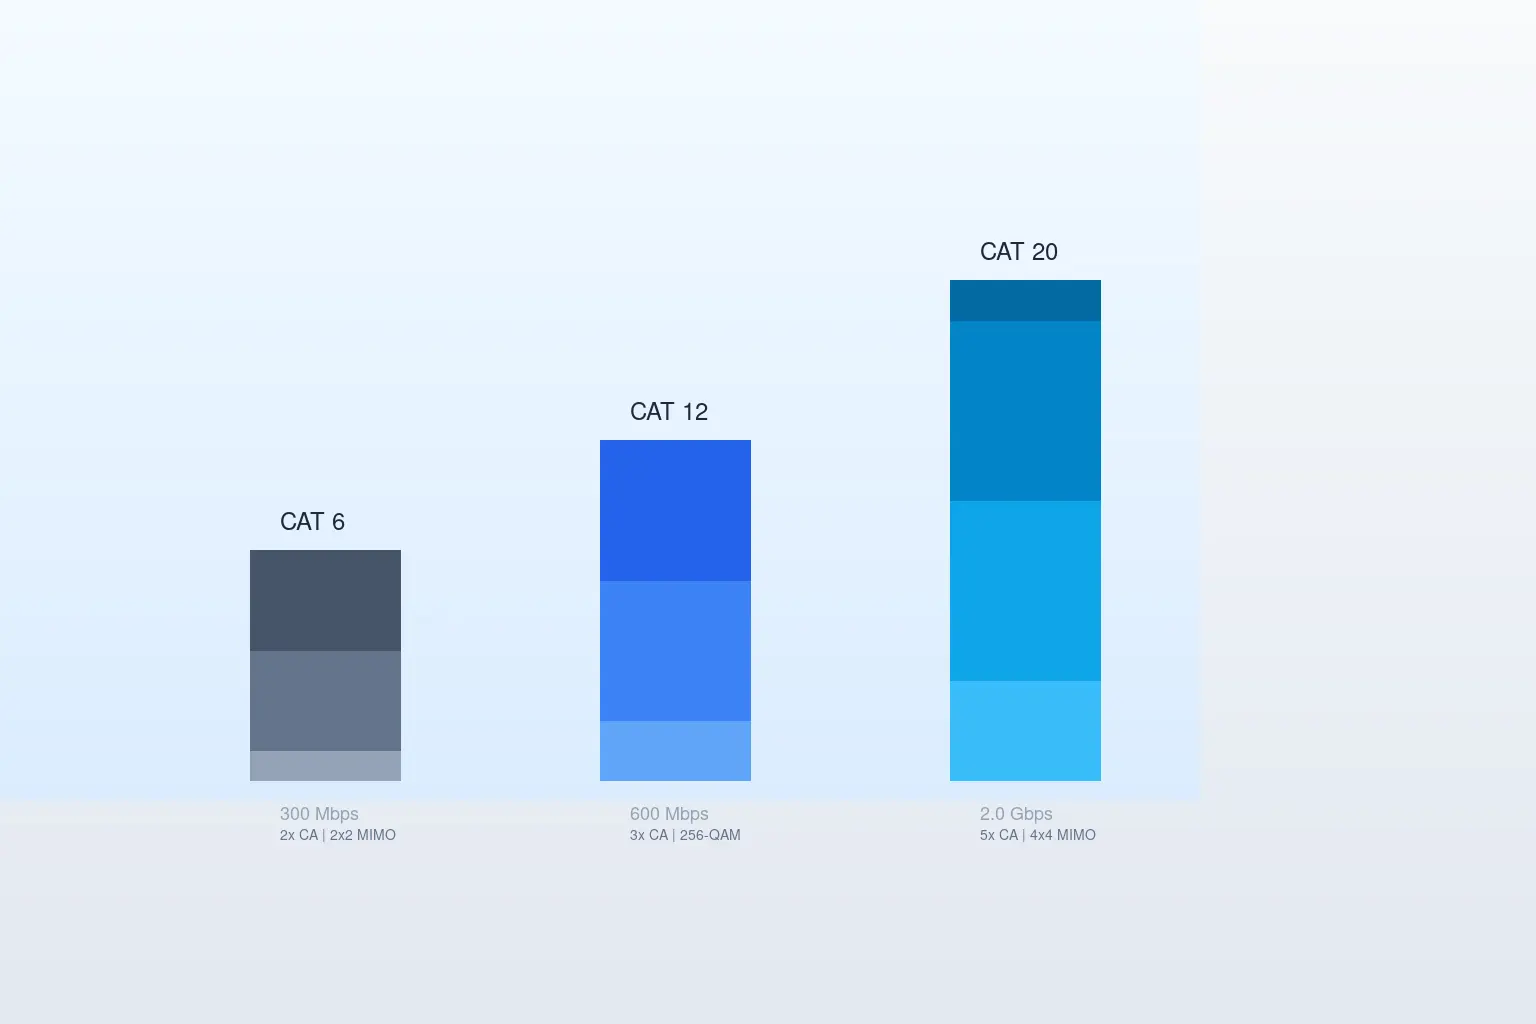
    Parameter Cat 6 Cat 12 Cat 20
    Max Downlink 300 Mbps 600 Mbps 2.0 Gbps
    Max Uplink 50 Mbps 150 Mbps 316 Mbps
    Carrier Aggregation 2× CA (20+20 MHz) 3× CA 5× CA
    MIMO Layers (DL) 2×2 2×2 or 4×4 4×4
    Modulation (DL) 64-QAM 256-QAM 256-QAM
    3GPP Release Rel 10/11 Rel 12 Rel 13/14
    Typical Real-World DL 80–180 Mbps 150–350 Mbps 300–800 Mbps

    Key takeaway: The jump from Cat 6 to Cat 12 is primarily about adding 256-QAM modulation and a third carrier, roughly doubling real-world throughput. The jump from Cat 12 to Cat 20 adds 4×4 MIMO and up to 5-carrier aggregation, enabling near-gigabit LTE performance — but requires significantly more spectrum availability at the tower side.

    Cat 6 CPE: The Cost-Effective Workhorse

    Best For

    • Rural and suburban FWA where spectrum aggregation is limited to two carriers
    • SMB backup internet and failover (typically paired with wired primary WAN)
    • IoT gateway and telemetry aggregation (low bandwidth, high device count)
    • Price-sensitive ISP deployments in emerging markets
    • Fixed-location retail POS and ATM connectivity

    Advantages

    • Lowest BOM cost: Cat 6 CPE modules and chipsets are the most mature and widely available, with module pricing typically 40-60% below Cat 12 equivalents.
    • Widest operator compatibility: Virtually every LTE network worldwide supports 2× carrier aggregation, making Cat 6 the most universally deployable category.
    • Lower power consumption: Typical Cat 6 CPE draws 5-8W under load, making it suitable for solar-powered or battery-backed remote deployments.
    • Proven reliability: Cat 6 has been in volume deployment for over 8 years; firmware and interoperability issues are well-understood and resolved.

    Limitations

    • Real-world throughput of 80-180 Mbps is insufficient for multi-user HD streaming or large file transfers in office environments.
    • 50 Mbps uplink ceiling limits cloud backup, video conferencing upload quality, and symmetrical enterprise applications.
    • Only 2×2 MIMO means weaker signal resilience at cell edge compared to 4×4 configurations.

    Cat 12 CPE: The Balanced Mid-Tier Performer

    Best For

    • Suburban and peri-urban FWA where operators have deployed 3-carrier aggregation
    • SME primary internet (10-50 users) where fiber is unavailable or uneconomical
    • Enterprise branch office primary or load-balanced WAN
    • Multi-tenant residential CPE (MDUs, student housing)
    • Operator-branded home broadband routers for markets with moderate spectrum depth

    Advantages

    • 256-QAM modulation delivers 33% more bits per symbol than Cat 6’s 64-QAM, significantly improving spectral efficiency.
    • 3× carrier aggregation allows the CPE to combine three separate LTE carriers, increasing aggregate bandwidth and improving load balancing across spectrum bands.
    • Optional 4×4 MIMO on some Cat 12 implementations provides better signal quality and throughput at medium-to-long range from the tower.
    • Solid uplink: 150 Mbps theoretical uplink (typically 40-80 Mbps real-world) supports cloud applications, video conferencing, and remote work use cases.

    Limitations

    • Performance is highly dependent on operator spectrum holdings — a Cat 12 CPE on a network with only 2 carriers will perform similarly to Cat 6.
    • Module and CPE BOM cost is 30-50% higher than Cat 6, which matters at ISP deployment scale.
    • Not all Cat 12 implementations include 4×4 MIMO; buyers must verify antenna configuration in the specific CPE model.

    Cat 20 CPE: Maximum LTE Performance for Demanding Deployments

    Best For

    • Enterprise headquarters and large branch offices (50+ users) requiring high-capacity wireless WAN
    • Operator FWA deployments in spectrum-rich markets (5+ carrier LTE networks)
    • Temporary event connectivity and rapid-deployment enterprise networks
    • High-definition video backhaul and surveillance aggregation
    • Markets where 5G NR coverage is not yet available but gigabit-class throughput is required

    Advantages

    • Gigabit-class LTE: With 5× carrier aggregation, 4×4 MIMO, and 256-QAM, Cat 20 can deliver 300-800 Mbps real-world downlink — competitive with entry-level 5G in many deployments.
    • 4×4 MIMO as standard: All Cat 20 devices support 4×4 MIMO on at least two carriers, providing superior signal resilience, cell-edge performance, and spatial multiplexing gain.
    • Highest uplink in LTE: 316 Mbps theoretical uplink (typically 80-150 Mbps real-world) supports symmetrical enterprise applications, cloud backup, and multi-user video conferencing.
    • Enhanced interference management: Cat 20’s 256-QAM with advanced receiver algorithms provides better throughput maintenance in high-interference urban environments.

    Limitations

    • Highest cost: Cat 20 modules can cost 2-3× more than Cat 6 equivalents, and CPE BOM costs are proportionally higher due to additional RF paths, antennas, and processing requirements.
    • Spectrum-dependent: A Cat 20 CPE deployed on a network with only 2-3 carriers will not achieve its rated performance. Operators must have 5+ carriers available at the serving cell.
    • Higher power: Typical power draw of 10-15W under load requires consideration for thermal management and installation location.

    Decision Framework: How to Choose

    Rather than selecting based on category number alone, B2B buyers should evaluate their deployment against these five criteria:

    1. Operator spectrum profile: Request the operator’s carrier aggregation configuration at the target deployment site. A Cat 20 CPE on a 2-carrier network is wasted investment; a Cat 6 CPE on a 5-carrier network leaves significant capacity unused.
    2. User count and application profile: For 1-5 users doing web/email (30 Mbps actual needed), Cat 6 suffices. For 10-30 users with video conferencing and cloud apps (100-200 Mbps), Cat 12 is the sweet spot. For 50+ users or HD video backhaul (300+ Mbps), choose Cat 20.
    3. Uplink requirements: If your deployment involves cloud backup, surveillance upload, or symmetrical applications, pay close attention to uplink specifications. The 50 Mbps Cat 6 uplink ceiling can be a bottleneck even when downlink is adequate.
    4. Deployment lifespan: A CPE purchased today for a 5-year deployment should account for growing bandwidth demand. Many ISPs are finding that Cat 6 deployments from 2021-2022 are now bandwidth-constrained; Cat 12 or Cat 20 provides more headroom for 2026-2031.
    5. Total cost of ownership (TCO): Include not just the CPE unit cost but also installation complexity (more antennas for Cat 20), power consumption, and potential truck-roll costs for mid-life upgrades. For large-scale ISP deployments, the Cat 6-to-Cat 12 TCO differential can influence per-subscriber margin by 8-15%.

    Honlly Telecom’s LTE CPE Portfolio

    Honlly Telecom offers OEM/ODM LTE CPE solutions across Cat 4, Cat 6, Cat 12, and Cat 20 categories, with flexible band configurations tailored to regional operator requirements. Our B2B customers can select from indoor desktop CPE, outdoor CPE with IP67 enclosure, and industrial-grade routers with extended temperature ranges. All platforms support cloud-based TR-069/TR-369 remote management and can be white-labeled with custom branding, firmware, and packaging.

    Contact the Honlly Telecom B2B sales team to discuss your LTE CPE deployment requirements and request evaluation samples.

  • Global Wi-Fi 7 Enterprise CPE Shipments Enter Volume Ramp in H2 2026 as Operators and ISPs Begin 802.11be Transition for Multi-Gigabit FWA

    Global Wi-Fi 7 Enterprise CPE Shipments Enter Volume Ramp in H2 2026 as Operators and ISPs Begin 802.11be Transition for Multi-Gigabit FWA

    The global Wi-Fi 7 (802.11be) enterprise CPE market is entering a significant volume ramp in the second half of 2026, as semiconductor supply chains stabilize and operator procurement frameworks mature. After two years of chipset qualification cycles and early adopter trials, the industry is now seeing commercial-scale orders from Tier-1 operators, managed service providers, and enterprise IT buyers across North America, Europe, and Asia-Pacific.

    From Standard Ratification to Volume Deployment

    The IEEE 802.11be standard reached formal ratification in early 2025, but the transition from standard finalization to volume CPE production has followed a predictable 18-to-24-month cycle. Key milestones in 2026 include:

    • Chipset maturity: Broadcom, Qualcomm, and MediaTek have all released second-generation Wi-Fi 7 SoCs with improved power efficiency and lower BOM costs, enabling CPE vendors to target sub-$150 enterprise access point price points.
    • Interoperability certification: The Wi-Fi Alliance’s Wi-Fi CERTIFIED 7 program has now certified over 400 devices, giving operators confidence in multi-vendor deployment scenarios.
    • Spectrum availability: The 6 GHz band (5925-7125 MHz) is now available for unlicensed use in over 70 countries, including the US, Canada, UK, EU, Japan, South Korea, and Australia, providing the 320 MHz channel width that differentiates Wi-Fi 7 from Wi-Fi 6/6E.

    What Wi-Fi 7 Brings to B2B CPE Deployments

    For operators and ISPs deploying fixed wireless access (FWA) CPE, Wi-Fi 7 is not merely an incremental upgrade. The standard introduces several architectural changes that directly impact enterprise deployment economics:

    Multi-Link Operation (MLO)

    MLO allows a Wi-Fi 7 CPE to simultaneously transmit and receive across multiple frequency bands (2.4 GHz, 5 GHz, and 6 GHz) on a single aggregated link. In practice, this means an enterprise FWA gateway can use the 6 GHz band for high-throughput backhaul while maintaining 5 GHz and 2.4 GHz for client access — all without the throughput penalty of traditional band steering. Early field data from operator trials shows MLO delivering 40-60% latency reduction in congested multi-tenant environments.

    4K QAM and 320 MHz Channels

    Wi-Fi 7’s 4096-QAM modulation, combined with 320 MHz channel bandwidth, pushes theoretical per-link throughput to 5.8 Gbps — nearly 5× the practical throughput of a Wi-Fi 6 2×2 configuration. For B2B buyers deploying cloud-managed branch office gateways, this means a single Wi-Fi 7 CPE can serve as a credible alternative to wired Ethernet backhaul for bandwidth-intensive applications like 4K video conferencing, large-file CAD/CAM transfers, and real-time IoT data aggregation.

    Multi-RU Puncturing

    Unlike Wi-Fi 6, where a single interferer on a resource unit (RU) could block an entire channel, Wi-Fi 7 supports preamble puncturing — allowing the CPE to use the clean portions of a channel while avoiding only the interfered sub-channels. This is particularly valuable in enterprise multi-tenant buildings, spectrum-congested urban deployments, and industrial environments with high EMI, where consistent throughput has historically been a challenge for wireless backhaul.

    Operator Procurement Trends in H2 2026

    Several procurement patterns are emerging as operators transition to Wi-Fi 7 CPE:

    • Dual-stack Wi-Fi 6E/7 gateways: Operators are favoring CPE that supports Wi-Fi 7 on the LAN side while maintaining Wi-Fi 6E fallback, allowing them to ship unified hardware that covers both current and next-generation subscriber premises without provisioning two separate SKUs.
    • 5G FWA + Wi-Fi 7 convergence: The combination of 5G NR WAN (delivering 1-3 Gbps downlink via mid-band spectrum) and Wi-Fi 7 LAN is emerging as the preferred architecture for fixed wireless operators competing against fiber. A 5G+Wi-Fi 7 gateway can credibly match or exceed the end-user experience of a GPON fiber deployment, at a fraction of the civil engineering cost.
    • Open-source CPE software stacks: Operators are increasingly requesting prplOS, RDK-B, and OpenWrt-based Wi-Fi 7 CPE platforms to avoid vendor lock-in and enable carrier-specific service differentiation through software customization.
    • Cloud-managed enterprise APs: Managed service providers are driving demand for Wi-Fi 7 access points with integrated cloud controllers, supporting zero-touch provisioning, AI-driven RF optimization, and per-application QoS policies.

    Implications for Honlly Telecom’s B2B Portfolio

    For Honlly Telecom and our B2B customers — ISPs, operators, MVNOs, and enterprise networking buyers — the Wi-Fi 7 transition represents both an opportunity and a procurement consideration:

    • CPE refresh cycles: Enterprise customers with Wi-Fi 5 or early Wi-Fi 6 deployments are entering a natural 3-5 year refresh window in 2026-2027. A Wi-Fi 7-capable CPE deployment now is a future-proof investment that will serve through the 2030 replacement cycle.
    • OEM/ODM readiness: Honlly’s R&D team is actively qualifying Wi-Fi 7 chipset platforms and antenna designs to ensure our B2B CPE portfolio supports 802.11be across 4G, 5G, and multi-WAN product lines.
    • Backward compatibility: Wi-Fi 7 is fully backward-compatible with Wi-Fi 6/6E/5/4 clients, meaning operators can deploy Wi-Fi 7 CPE today and realize immediate client-side benefits while preparing for next-generation throughput as subscriber devices upgrade.

    Market Outlook and Forecast

    Industry analysts project Wi-Fi 7 enterprise CPE shipments to exceed 50 million units in 2027, growing at a compound annual rate exceeding 60% from 2026 to 2030. The enterprise access point segment alone is expected to account for approximately 35% of total Wi-Fi 7 chipset shipments. For B2B buyers, the window for strategic CPE selection and qualification is now — before the 2027 volume-driven supply constraints that typically accompany major Wi-Fi generation transitions.

    Summary

    Wi-Fi 7 is no longer a roadmap item. It is a volume-shipping product category in H2 2026 with mature silicon, certified interoperability, and growing operator procurement frameworks. For ISPs, operators, and enterprise buyers evaluating their next CPE generation, the question is shifting from “Should we plan for Wi-Fi 7?” to “How quickly can we qualify and deploy?” Honlly Telecom is positioned to support B2B customers through this transition with OEM/ODM Wi-Fi 7 CPE solutions tailored to carrier and enterprise deployment requirements.

    For more information about Honlly Telecom’s Wi-Fi 7 CPE roadmap and OEM/ODM partnership opportunities, contact our B2B sales team.

  • Private 5G (NPN) CPE Deployments Accelerate as Enterprises Build Non-Public Networks for Industry 4.0 Manufacturing in 2026

    Private 5G (NPN) CPE Deployments Accelerate as Enterprises Build Non-Public Networks for Industry 4.0 Manufacturing in 2026

    Manufacturing enterprises worldwide are accelerating the deployment of private 5G networks, also known as Non-Public Networks (NPN), as Industry 4.0 initiatives demand deterministic connectivity, ultra-low latency, and complete data sovereignty. At the center of these deployments sits a critical hardware component: the Private 5G NPN Customer Premises Equipment (CPE).

    For telecom operators, system integrators, and B2B distributors serving industrial customers, understanding the unique requirements of NPN-certified CPE — and how they differ from public 5G FWA gateways — has become essential to winning Industry 4.0 procurement contracts in 2026.

    The NPN CPE Difference: What Makes Private 5G Hardware Unique

    Unlike consumer-grade or standard enterprise FWA routers, NPN CPE devices must meet several specialized requirements mandated by 3GPP Release 17/18 specifications for standalone private networks:

    1. SNPN (Standalone Non-Public Network) Authentication: Private 5G CPE must support Network Identifier (NID)-based network selection, enabling devices to discover and attach exclusively to a specific enterprise’s private network rather than scanning public PLMN IDs. This prevents unauthorized roaming and ensures data never traverses public infrastructure.

    2. Local Breakout and Edge Compute Integration: NPN CPE frequently serves as an on-premises edge node, hosting local UPF (User Plane Function) capabilities. This enables manufacturing data — from PLC controllers, vision inspection systems, and AGV telemetry — to be processed within the factory perimeter without WAN round-trips, achieving sub-5ms latency for closed-loop control applications.

    3. Industrial Protocol Bridging: The CPE must natively bridge 5G NPN connectivity to industrial protocols including PROFINET, EtherCAT, Modbus TCP, and OPC UA. Leading NPN CPE designs now incorporate protocol conversion at the hardware level, eliminating the need for separate industrial gateways.

    4. Ruggedized Form Factors for Factory Floors: Manufacturing environments demand IP65+ rated enclosures, extended temperature ranges (-40°C to +75°C), vibration resistance per IEC 60068, and DIN-rail mounting compatibility — specifications rarely found in commercial FWA equipment.

    Deployment Models Gaining Traction in 2026

    Three deployment architectures have emerged as dominant patterns across the private 5G market:

    Model A — Fully Isolated NPN: The enterprise owns all network elements including the 5G core, RAN, and CPE fleet. Common in automotive manufacturing, defense, and semiconductor fabs where data sovereignty is non-negotiable. CPE requirements include SNPN-only operation, local AAA server integration, and zero backhaul to public networks.

    Model B — Hybrid Public-Private with Network Slicing: The CPE connects to both a public 5G macro network (for general internet access) and a dedicated NPN slice (for production traffic). This architecture demands CPE with dual-SIM or multi-PDU session support, VLAN segmentation between production and IT traffic, and slice-aware QoS policies.

    Model C — Operator-Hosted NPN: A mobile network operator deploys and manages the private 5G infrastructure as a managed service, with dedicated spectrum (often in n77, n78, or n79 bands) and a hosted 5G core instance. CPE in this model must support operator-specific NPN configurations while maintaining logical isolation from the operator’s public subscriber base.

    Spectrum Considerations for NPN CPE

    The global spectrum landscape for private 5G continues to mature. Key bands for NPN CPE procurement include:

    • n77 (3.7 GHz) / n78 (3.5 GHz): The most widely allocated private 5G bands globally, supported by regulatory frameworks in Germany (3.7-3.8 GHz), Japan (4.6-4.9 GHz), the UK (3.8-4.2 GHz shared access), and the US (CBRS 3.55-3.7 GHz). NPN CPE must support these bands with carrier aggregation for throughput-intensive applications like machine vision.
    • n79 (4.7 GHz): Increasingly allocated for industrial private networks in Asia-Pacific markets, requiring CPE with extended high-band RF front-end designs.
    • mmWave (n258/n257): Deployed in factory micro-cells for ultra-high-capacity applications including real-time 8K quality inspection and digital twin synchronization, demanding beamforming-capable mmWave CPE modules.

    Procurement Checklist for B2B Buyers

    Operators and distributors evaluating NPN CPE for industrial customers should verify the following capabilities:

    • 3GPP Release 17/18 SNPN and CAG (Closed Access Group) certification
    • Multi-band support covering the target private spectrum allocation in deployment countries
    • Local UPF integration capability and edge compute API availability
    • Industrial protocol support (PROFINET, EtherCAT, Modbus, OPC UA)
    • IP65+ environmental rating with extended temperature range
    • TR-369 USP or NETCONF/YANG-based remote management
    • TSN (Time-Sensitive Networking) support for deterministic manufacturing traffic
    • Dual PDU session capability for hybrid deployment models
    • Hardware root of trust and secure boot for industrial OT security

    Market Outlook 2026-2027

    The private 5G CPE market is projected to grow at 38% CAGR through 2028, driven by manufacturing digitization initiatives in Europe, Industry 4.0 mandates across Asia-Pacific, and reshoring-driven factory modernization in North America. For OEM/ODM CPE manufacturers, the opportunity lies in delivering NPN-certified hardware platforms that combine carrier-grade reliability with industrial-grade ruggedization — at price points that make private 5G economically viable for mid-sized manufacturing enterprises.

    As the ecosystem matures, the convergence of NPN CPE with on-device AI inference, digital twin integration, and predictive maintenance analytics will further differentiate leading hardware platforms. B2B buyers should prioritize CPE vendors with demonstrated NPN certification track records and the manufacturing scale to support large-volume industrial deployments across multiple geographies.